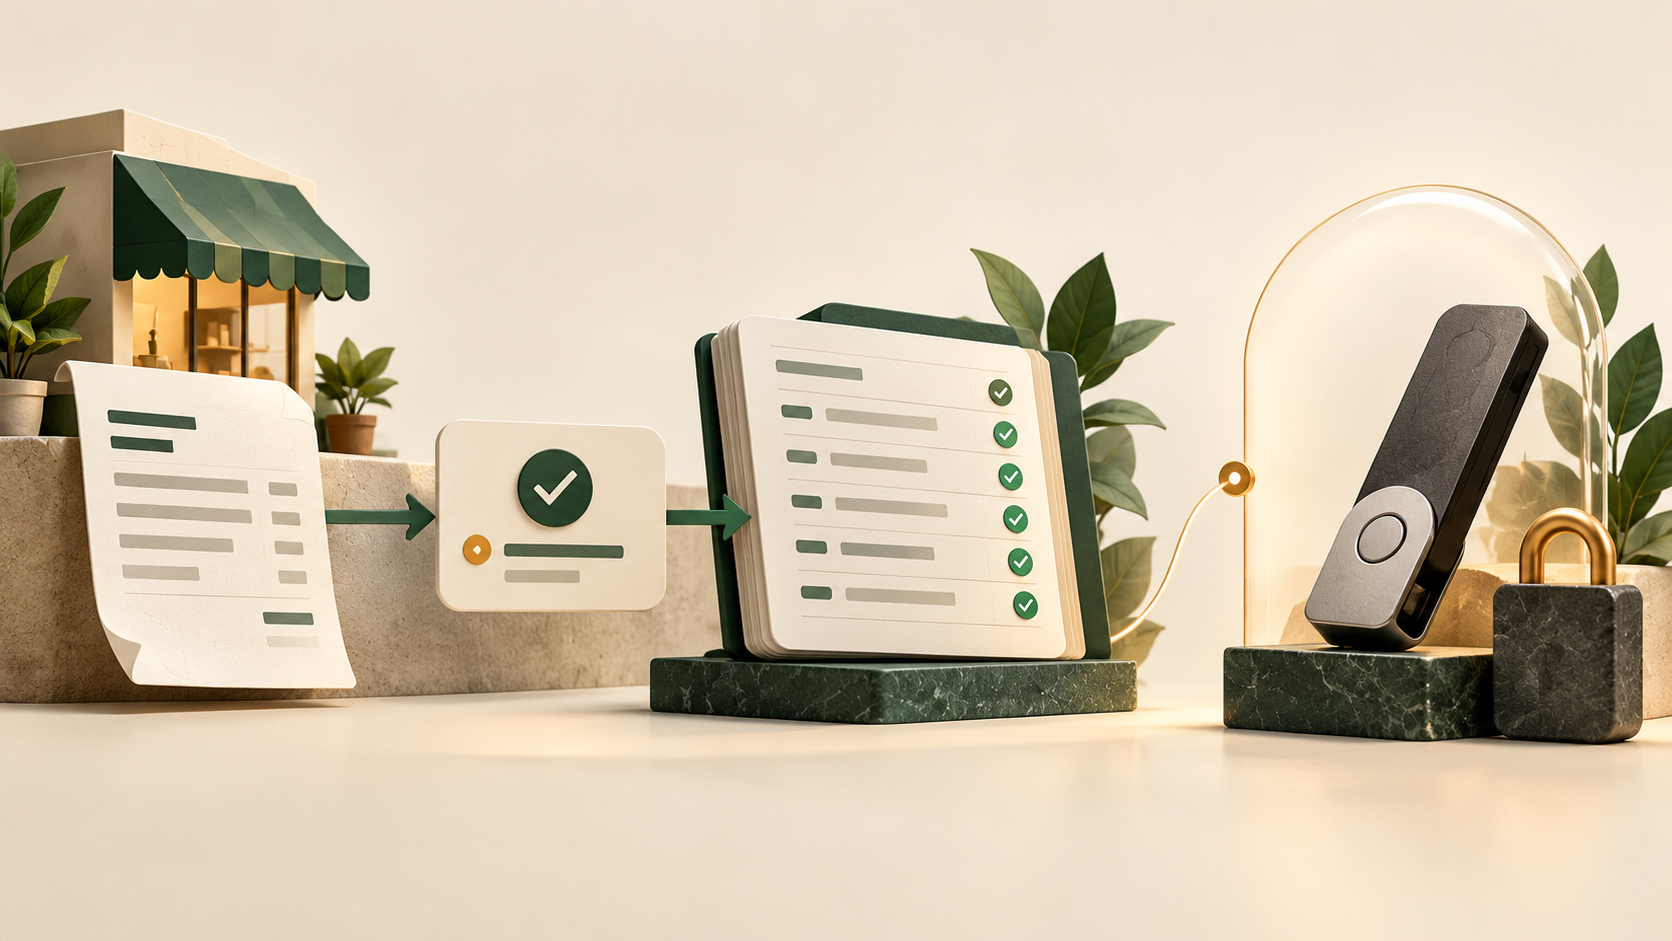
A crypto payment can appear in a wallet while the related invoice is still unresolved: the amount may be short, the reference may be missing, or the transaction may not have enough confirmations for the merchant’s policy. A documented automated invoice management workflow can keep invoice IDs, payment status, evidence, and exceptions together. It does not replace wallet-security controls, which should be designed separately and never depend on sharing a seed phrase or private key.
Keep payment verification separate from wallet access
A payment workflow answers operational questions: which invoice is this, what amount was expected, what transaction is being reviewed, and who may mark the invoice settled? Wallet security answers a different question: who can authorize a transfer or recover the wallet? A reliable process connects the records without giving invoicing staff access to signing keys they do not need.
For a small business, write a short policy before accepting a digital asset. Name the person who checks transactions, the confirmation rule, the approved receiving address, the record-retention location, and the escalation path for mismatches. Keep signing authority and reconciliation authority distinct wherever practical. A spreadsheet or payment dashboard should never contain a seed phrase, private key, recovery file, or unencrypted wallet export.
What a merchant should confirm before marking an invoice paid
Do not treat a screenshot, email notification, or customer-provided transaction hash as conclusive on its own. Verify the transaction using a trusted source for the relevant network, then compare it with the invoice and the merchant’s own policy. The exact checks depend on the asset and network; do not assume that a process suitable for one chain applies to another.
- Invoice identity: match the invoice number or payment reference, customer, and order.
- Receiving destination: confirm that the transaction was sent to the address designated for this payment.
- Asset and network: make sure the transferred asset and network are the ones the business agreed to accept.
- Amount and denomination: record the on-chain amount and the conversion method, timestamp, and reference rate used for accounting where relevant.
- Transaction state: apply the business’s confirmation and finality policy before releasing goods or closing the receivable.
- Fees and short payments: record any network or intermediary fees separately instead of silently changing the invoice amount.
These steps are control points, not investment advice. A payment can be visible but still be pending, replaced, sent on the wrong network, or unrelated to the invoice. If the evidence is ambiguous, leave the invoice in a review state and ask a second authorized person to resolve the exception.
Use a receiving-wallet model that limits exposure
Choose the wallet arrangement around the business’s threat model and transaction volume. A hot wallet may be operationally convenient for frequent receipts, but online access raises the importance of device security, account separation, and withdrawal limits. A cold-storage setup may reduce online exposure for reserves, but it adds signing, recovery, and continuity procedures. Neither label alone proves that a wallet is safe.
Separate routine receiving from treasury storage when the business can support the added process. Set a documented threshold for moving funds, require independent approval for high-value transfers, and verify address changes through a second channel. If a wallet is used by more than one person, define who can view balances, prepare a transaction, approve it, and recover access. Avoid shared browser profiles and shared recovery phrases.
For background on custody trade-offs, see the site’s guide to hot wallets versus cold wallets. The right choice depends on how quickly funds must be accessed, who holds the signing authority, what happens if a device is lost, and how the organization verifies a recovery procedure.
A simple payment-to-ledger workflow
- Create the invoice. Give it a unique ID, amount, currency or asset, due date, customer, and clear payment instructions.
- Record the expected destination. Use an approved receiving-address process. If a new address is introduced, have an authorized reviewer verify it before the invoice is sent.
- Monitor without exposing keys. Reconciliation staff should be able to check incoming activity through a read-only view or trusted explorer without gaining signing authority.
- Match evidence. Compare the transaction, invoice, amount, asset, network, recipient, and status. Preserve the transaction reference and the time of verification.
- Resolve exceptions. Route underpayments, overpayments, wrong-network transfers, duplicate payments, and unclear references to a named reviewer.
- Close the record. Mark the invoice paid only after the policy’s verification condition is met, and keep the evidence with the accounting entry.
Compare workflow approaches
The options below describe different ways to organize invoice records and reconciliation. They are not claims that any provider supports a particular crypto asset or blockchain. Confirm capabilities, eligibility, supported jurisdictions, and pricing directly before relying on a service.
| Approach | May suit | Checks and limitations |
|---|---|---|
| 1. Performa Finance invoice-workflow reference | Teams researching how invoice creation, status tracking, and exception handling can be organized. | Review the linked invoice-management material and verify current product scope directly; it does not establish support for a particular crypto asset, network, custody model, or settlement method. |
| 2. Existing accounting platform | A business that already maintains customer records and a general ledger in one system. | Check how verified transaction evidence is imported, how partial payments are recorded, and whether the audit trail is retained. |
| 3. Controlled spreadsheet | Very low payment volume with one clearly assigned reviewer. | Use access controls, change history, backups, and a separate secure wallet process; spreadsheets can become inconsistent as volume grows. |
| 4. Custom reconciliation workflow | A team with repeatable rules that existing tools cannot represent. | Account for integration maintenance, chain-specific edge cases, security reviews, and a manual fallback when a data source is unavailable. |
Protect the recovery path
Wallet recovery is a high-impact operation. Follow the wallet provider’s official documentation, use an offline recovery procedure, and restrict access to the people who genuinely need it. Never enter a recovery phrase into a website, form, support chat, or unsolicited “verification” page. A legitimate invoice, block explorer, or reconciliation spreadsheet does not need a seed phrase.
Phishing often imitates wallet support, token claims, transaction alerts, or a familiar domain with a small spelling change. Use bookmarks for critical services, verify the site address before signing, and treat unexpected requests to connect a wallet or reveal recovery words as a warning. The site’s guide to common seed phrase scams covers related red flags.
Keep business records out of wallet recovery materials. An invoice may contain customer names, commercial terms, or tax information; store it in an access-controlled business system. A recovery phrase should not be attached to the invoice, kept in the same cloud folder, or sent to the person responsible for routine accounts receivable.
Design an exception process before the first mismatch
Decide in advance what happens when a transaction is underpaid, overpaid, delayed, duplicated, or sent to an unexpected address. The person handling a customer conversation should not be able to change the receiving address and approve the resulting payment alone. For high-value or unusual transactions, pause fulfillment until a second reviewer has checked the facts.
Preserve the original invoice, any revised instructions, transaction reference, verification timestamp, reviewer, and decision. If a correction is needed, create a clear adjustment or replacement record rather than overwriting history. This makes later accounting review more reliable and helps the business explain its decision to the customer.
Questions to ask before accepting crypto payments
- Which assets and networks will the business accept, and who approves a change?
- What confirmation threshold applies before goods are released or an invoice is closed?
- Who can view balances, prepare transfers, approve transfers, and recover the wallet?
- How will exchange-rate references, fees, partial payments, and refunds be documented?
- Where will invoice and transaction records be retained, and who can access them?
- What is the safe fallback if a wallet, explorer, or accounting integration is unavailable?
These questions make the process auditable without turning ordinary invoice work into wallet administration. Keep the policy short enough that staff can follow it, and review it when the business changes its assets, providers, transaction volume, or signing model.
FAQ
Does a transaction screenshot prove that an invoice is paid?
No. A screenshot is supporting evidence, not a substitute for independent verification. Check the transaction through a trusted source and apply the business’s status and confirmation policy.
Should accounts-receivable staff have the seed phrase?
Usually not. Reconciliation staff need enough access to verify records, but routine invoice matching does not require authority to recover or sign from a wallet.
Can a business use one wallet for every customer payment?
That depends on the business’s controls, privacy needs, and accounting process. If an address is reused, understand the resulting traceability and operational risks; document how each transaction will be matched to an invoice.
What should happen when the amount does not match?
Keep the invoice open or in review, preserve the transaction details, and use a documented exception process. Do not silently mark it paid or change the invoice history.
Does invoice-management software verify crypto transactions?
Not necessarily. Invoice workflow tools and blockchain verification are separate capabilities. Check the provider’s current documentation and the specific assets, networks, and integrations before relying on a tool.
What is the safest first step for a small business?
Write down who verifies payments, what evidence is required, how mismatches are escalated, and how wallet recovery is protected. Test the process with a low-risk scenario before making it part of routine operations.